
Found the business? Finance the whole thing — goodwill included.
Welcome, SMB Deal Hunters. When a listing deserves a closer look, T Bank’s Audrey Wendel and Glenn Giro are the SBA lending team that gets those purchases financed. Bring them the business you’ve found, or the question you’re stuck on — at any stage. Their job is to make the path from first look to closing clear, and to make sure the financing is the simplest part of it.
We'll fund it.
How do SBA loans for buying a business work?
An SBA 7(a) loan lets you buy an existing business with the government guaranteeing most of the loan, which is what allows a bank to finance the purchase, goodwill included, with a smaller down payment than conventional credit requires. You bring the listing and a short set of initial documents. We underwrite the business’s cash flow, work out the structure, and issue the term sheet. Closings are subject to credit approval.
Signed the LOI? Start these the same day.
The fastest files are the ones where the buyer runs ahead of us. Seven moves that keep your closing moving:
Then expect our business questionnaire.
Eight short sections, about five minutes each. It tells your underwriter the story behind the numbers.
Your Dedicated Lending Team
One inbox. Someone always answers.
Write to [email protected] and both Audrey and Glenn see it.
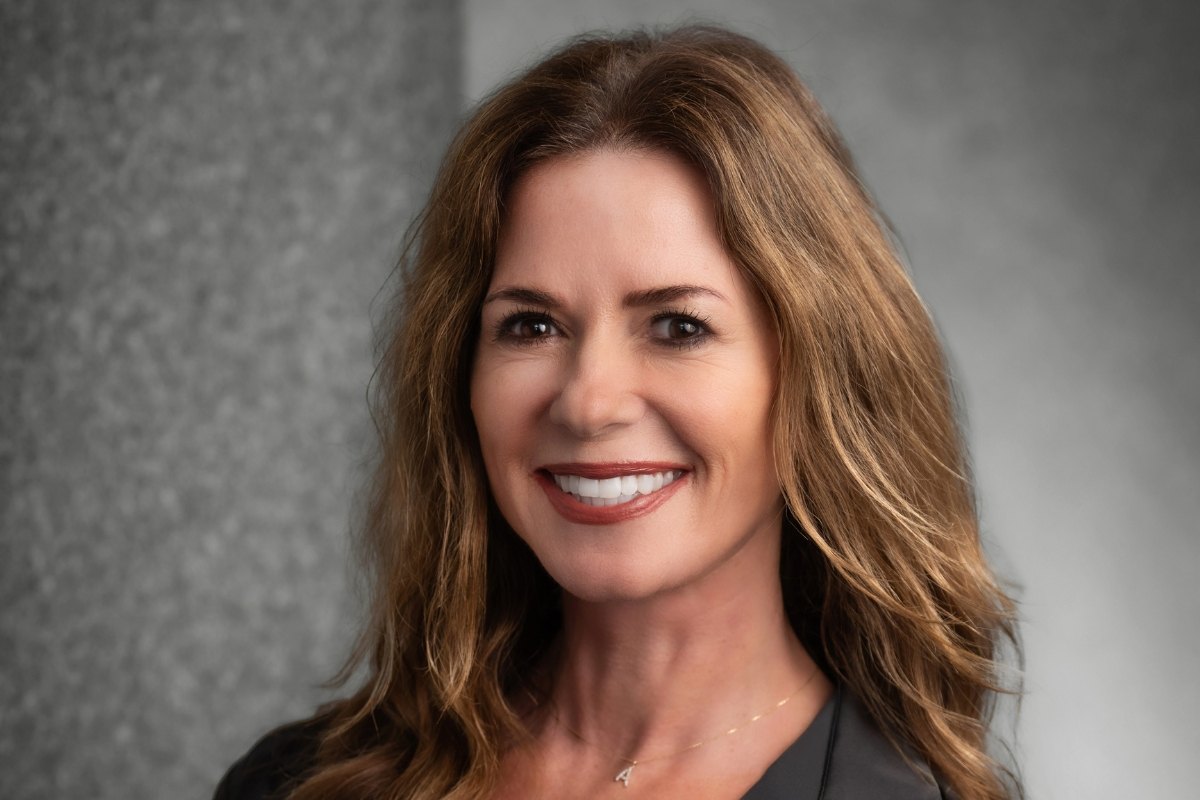
Audrey Wendel
Audrey joined T Bank in 2006 to launch its highly successful national dental-practice program, and those first closings taught her how powerful the right financing can be. Since then, she’s brought the same hands-on approach to full-scale SBA lending for business acquisitions — everything from first-time buyers taking over a single location to multi-practice roll-ups that need creative, cash-friendly structures.
Audrey is the person who translates lender jargon into understandable terms, keeps the timeline honest, and makes sure the closing table feels a lot less scary than it sounds. Her goal is always the same: recommend the right loan, not just any loan, and remain a resource long after closing.
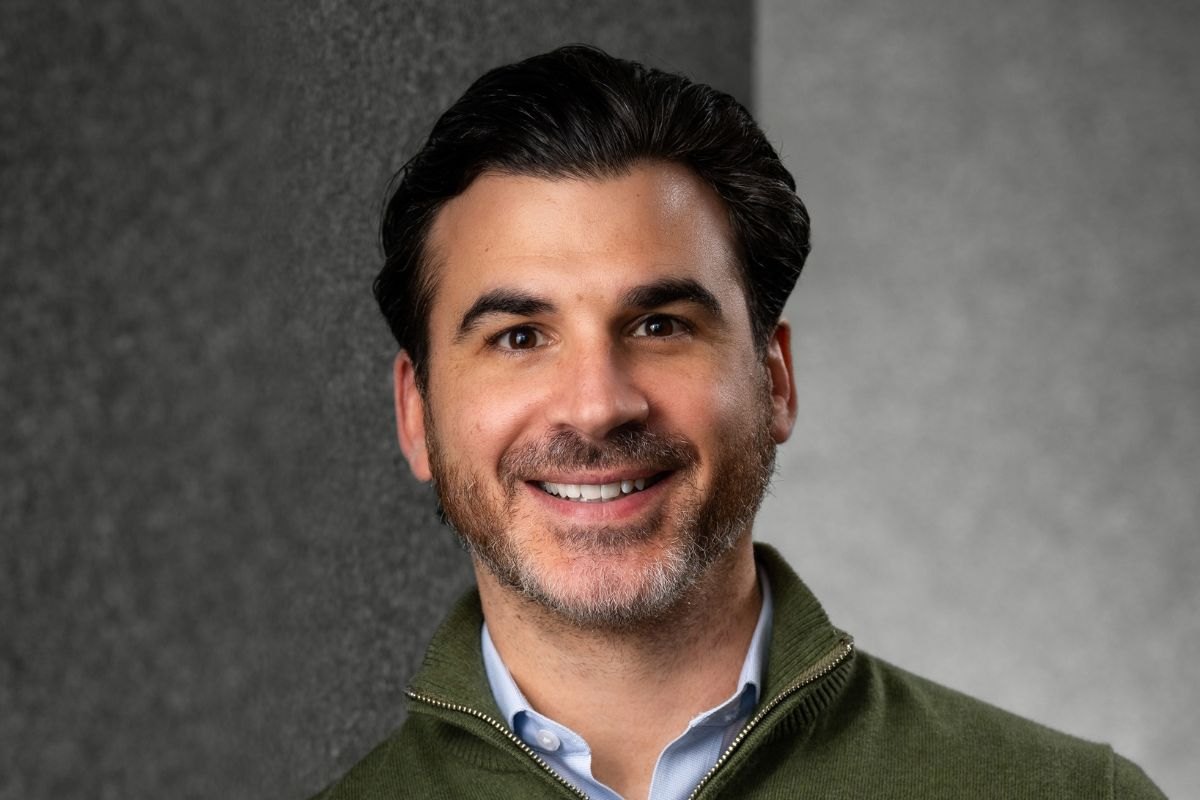
Glenn Giro
Glenn has lived on the front line of SBA lending since 2008 — credit, cash-management, and the art of getting a loan across the goal line. After 13 years in Chicago structuring growth capital, he moved back to Tennessee to focus on what he enjoys most: helping entrepreneurs buy, build, and eventually exit businesses on their own terms.
He regularly hosts the “SBA University” podcast, breaking down process and policy into plain English so buyers and advisors know exactly what to expect. Whether it’s an acquisition, a multi-location roll-up, or a partner buyout, Glenn stays in constant contact, lays out a clear path, and makes sure financing is the simplest part of your growth story.
SBA University
Your SBA loan questions, answered.
Glenn hosts SBA University, a regular lesson that breaks down SBA process and policy into plain English — how acquisition financing is structured, what underwriters actually look for, and what to expect at each step. If you’re still in the hunting stage, it’s the best place to learn how the money side works before you write an offer.
Go Deeper
Start wherever you are.
The topics buyers ask Audrey and Glenn about most. Bring any of them to your first call.
As little as 10% down, goodwill included — how acquisition financing is put together.
Every step from term sheet to closing, in order, with honest timelines.
Every document a lender will ask for. We’ll send you the full list, so you can start collecting now.
Which program fits what you’re buying: the business, the building, or both.
Send us a listing and we’ll estimate the monthly payment, usually in about a minute.
Smaller purchases: where to look, and why an SBA Express loan may be faster.
Recent T Bank closings — the industries, structures and amounts we fund.
Lender jargon, translated. Ask us about any term you hear.
Why T Bank
Built for a faster yes — and one that holds.
An SBA Preferred Lender. One team, from first call to funded.
We lend on the business, not the furniture
A good acquisition is mostly goodwill: the cash flow, the customer list, the name. Banks that need hard collateral can’t get there. We finance the real value, typically with 10–15% down.
Fast enough to win it
A written term sheet and a buyer letter you can show a seller, within 48 hours of a complete file. When two buyers want the same business, the one who looks funded usually wins.
Approvals built to finish
Credit decisions are made in-house, under delegated SBA authority. When your file gets its initial go-ahead at prequal, it also gets an executive’s buy-in, and that executive supports it at the loan committee for final approval. So a first yes tends to hold. No surprises at the end.
Any listing, any state
Your search shouldn’t be limited by your bank’s footprint. We lend in all fifty states, $500K to $25M, with more than $2 billion in SBA loans funded (per SBA DFW District Office).
Closed Loans
Recently closed for buyers like you.
These files closed on Audrey and Glenn’s desk, including four they worked together.
Acquisition of an experiential marketing firm.
SBA 7(a)
Acquisition of a design-industry bookkeeping firm, plus working capital.
SBA 7(a)
A wholesale chemical distributor acquisition plus working capital.
SBA 7(a) — California
Acquisition of an established electrical company.
Georgia
Acquisition of a diesel pickup-truck repair shop including its real estate.
SBA 7(a) — Texas
Acquisition of an office equipment company by a longtime employee.
SBA 7(a) — Tennessee
Acquisition of a full-service home improvement center.
SBA 7(a) — Illinois
A transmission repair shop acquisition including its real estate, plus working capital.
SBA 7(a) — Tennessee
Closings are subject to credit approval. Stated timelines apply to qualified submissions and are contingent upon the applicant’s timely submission of all required documentation.
Have a listing in front of you? A ten-minute call is enough for a candid read.
FAQs
Before you ask.
I found a business through SMB Deal Hunter. What should I send you first?
Start with a note about the business: the listing link, the industry, the price. From there it’s a ten-minute call to see if T Bank fits your plans. If it does, we’ll send a secure upload link for documents; nothing travels over plain email. And if the numbers work, a term sheet and buyer letter can follow within two business days.
How much do I need to put down?
SBA acquisition financing can require as little as 10% down, and seller notes can be part of the structure. For planning, have liquidity for a 10–15% down payment; we’ll walk you through the exact figure for your purchase.
How long does the loan funding process take after I’m prequalified?
Once you’re pre-qualified, the timeline for closing a loan can vary, but our streamlined, in-house approval process is designed for efficiency and speed. A significant factor in the timeline is how quickly you can provide the necessary documentation, such as personal and business tax returns. The faster you provide the required documents, the faster we can move toward closing your loan.
What if I don’t have experience in the industry I want to buy into?
Your relevant skills, licenses, and personal bio can demonstrate your expertise and commitment to run the business. We also look for a solid plan for the business post-closing, including how you’ll manage the team and any potential knowledge gaps.
How does T Bank’s SBA Preferred Lender status benefit me?
As a Preferred SBA Lender, we have the authority to approve loans in-house. This means we avoid the red tape of external SBA committees, leading to faster decisions and a more predictable closing process.
What is the minimum loan amount you provide?
Our loans range from $500K to $25M. Below $500K, we’re honestly not your fastest or cheapest path: an SBA Express loan from a local bank usually is. If your purchase is near the line, you’re still welcome to reach out, and we’re happy to point you toward the best options.
Do I have to live in a certain area to get a loan from T Bank?
No. We lend nationwide, with more than $2 billion in SBA loans funded, per SBA DFW District Office.
Let’s get your acquisition funded.
Missed a box? Talk to us anyway. There may still be a path.